 Varad
VERIFICATION OF VENDOR INVOICES
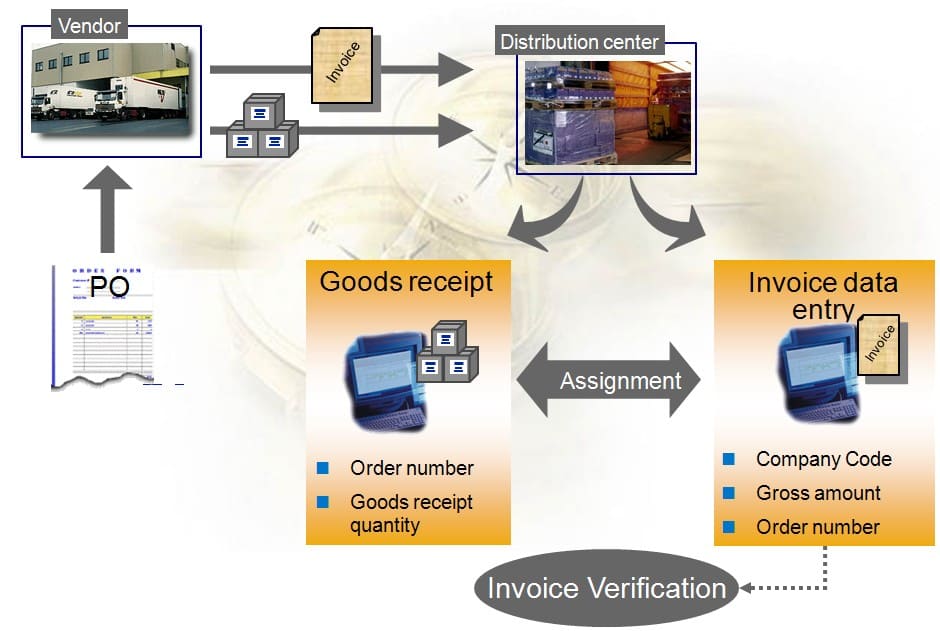
- The Materials Management Document contains detailed information on the invoice verification procedure.
The following entry will be made after the vendor bill is received: - Vendor Account CR; GR/IR Account DR; Freight Clearing Account DR; Cenvat Clearing Account DR
Verification of Invoice for Foreign Vendor
The following entry will be made after the vendor bill is received:
- Account Type: GR/IR DR
- Supplier Account CR
Verification of Invoice for Special Vendor
The following entry will be made after the vendor bill is received:
1) Part 2 A/C of RG 23A/RG 23C (CVD) Account DR Cenvat Clearing Account CR
2) Cenvat Clearing A/c DR and G/R I/R A/c DR
Supplier Account Number
3) Material Account Cost (DR) Vendor Account (Customs) CR
Verification of Invoice for Freight and Clearing Agent; Material Cost A/C DR; Vendor A/C (Clearing Agent) CR
- Verification of Invoice for Octroi Expenses
Vendor A/c (Octroi) CR Cost of Material DR - For service orders, TDS (Work Contract Tax) must be computed and subtracted appropriately.
Upon the passage of the measure, the following entry will be made: - The Costs Account DR
Supplier Account CR
TDS Account CR - Exchange discrepancies for capital items from import vendors must be manually recorded using a journal voucher for capitalization.
Differences in exchange rates will be recorded at HO. An illustration of the accounting entry in this scenario would be:
- Bill input at 40 INR = 1 USD
- Account for Asset/Expense DR 100
Provider A/C CR 100 - $1 USD at 41 INR for payment entry
Vendor account number 100
Bank Account Number (CR) 110
Capital A/c DR 10 Exchange rate loss
Exchange rate loss Capital A/c CR 10 Exchange rate loss Asset A/c 10
- For the unique G/L transactions, a new G/L account needs to be formed.
- The down payment will be recorded in the accounting as follows:
- Paying ahead to the supplier account
- Debit Bank Account Credit
The protocol should be adhered to is:
Definition of alternative accounts payable reconciliation used to post capital asset down payments
clearing the final invoice together with the upfront payment in accounts payable.
For the unique G/L transactions, a new G/L account needs to be formed.
The down payment will be recorded in the accounting as follows:
Vendor Advance for Capital Goods Account Credit/Debit from Bank Account
- Upon booking the invoice, the subsequent entry is made.
A/C Asset and WIP Asset Debit Account Number of Vendor Credit
Invoice clearance for the down payment
The vendor’s account number
Vendor Advance for Credit on Capital Goods Account - The TDS Rates are as follows (must be verified with the recent modifications)
Specifics Rate of Surcharge on Tax Rate 194 C contractors in total 5% 2.10% 2%
Promotion – 194 C 1% to 5% 1.05%
Professor Fees: 194 J 5% 5% 5.25%
Other Rent: 194 I 15% 5% 15.75%
Company rent: 194 I 20% 5% 21%
194H 5% 5% 5.25% Commission
194 A 10% 5% 10.50% Interest-Others
Interest: 194 A 20% 5% 21% Company
Works Contract Tax Special Concessional Tax - The vendors’ security deposits and the oldest money deposits received from them are as follows: Bank A/c DR Security Deposit Vendor CR
- In order for the EMD to be transferred to an unclaimed EMD account, the age must be provided.
TOUR ADVANCE PAYMENT FOR DOMESTIC TOURS
you may be interested in this blog here:-
How Many Employees Does Salesforce Have in 2024?